Is Buying a House Worth It in South Africa? Pros, Cons and Costs Explained
By Bongani Dube •
Published September 5, 2026 •
23 min read • Updated September 6, 2026
Is Buying a House Worth It in South Africa? Pros, Cons and Costs Explained
Is buying a house worth it in South Africa? For many people, yes—but only when the numbers and your circumstances make sense. Buying can be worthwhile if you can comfortably afford the bond and all the additional ownership costs, have emergency savings left after purchasing, and expect to stay in the property for several years. Renting may be the smarter option if buying would stretch your budget, your income is unstable, you may relocate soon, or renting a comparable home is significantly cheaper.
The mistake is assuming that buying is automatically better because “rent is paying someone else’s bond.” Homeownership can help you build an asset over time, but a house also comes with interest, rates, insurance, maintenance, transaction costs and potentially levies. Some of that money does not build equity either.
This News Domain opinion guide looks at both sides of buying a home in South Africa so you can decide whether ownership makes financial sense for you.
News Domain’s view: Buying a home can be a strong long-term financial decision, but affordability should come before ownership. A person who comfortably rents and saves is not necessarily in a worse financial position than someone struggling every month to keep a bond paid.
Table of Contents
Is Buying a House Worth It in South Africa? Quick Answer
Buying may be worth it when…
Renting may be better when…
You plan to stay for several years
You may relocate soon
Your income is reasonably stable
Your income is unpredictable
You have money for upfront costs
Buying would use all your savings
The bond comfortably fits your budget
The bond would stretch your budget
You have an emergency fund
You have no financial buffer
You want long-term ownership
You value flexibility
You understand maintenance costs
You don’t want repair responsibilities
You can handle interest-rate changes
A rate increase would put you under pressure
The property’s total cost makes sense
Comparable rent is substantially cheaper
The important word is comfortably.
A bank approving a home loan does not automatically mean purchasing at the maximum amount available is a good idea.
Why Do South Africans Want to Own Property?
Homeownership has powerful emotional and financial appeal.
For many households, owning a home represents:
security;
independence;
stability;
a place to raise a family;
freedom from a landlord;
an asset that may appreciate;
something that can eventually be owned without a bond; and
an asset that may potentially be passed to family.
Those are legitimate advantages.
But emotional value and financial value aren’t always identical.
You can love the idea of owning a house while still deciding that right now isn’t the correct time to buy one.
That isn’t necessarily a failure.
It can simply be a financial decision.
What Are the Biggest Advantages of Buying a House?
Homeownership can provide long-term stability and the opportunity to build equity, but it also comes with ongoing financial responsibilities.
Let’s start with the case for buying.
1. You Can Build Equity
One of the strongest arguments for ownership is equity.
When you rent, you pay for the right to occupy someone else’s property for a specified period.
When you buy with a bond, part of your repayments eventually reduces the amount owed on an asset you own.
Over a long enough period, you could reach a point where the home is fully paid off.
That creates a major difference between:
renting indefinitely
and
eventually owning your residence outright.
However, remember that a bond repayment isn’t entirely “saving.”
Part of the repayment goes toward interest, particularly during the earlier years of a long-term home loan.
2. Property Can Increase in Value
Property values can appreciate.
Imagine buying a property for R1.2 million and eventually selling it for considerably more.
That growth can contribute to your wealth.
But the word can matters.
Property prices are not guaranteed to increase quickly enough to make every purchase profitable.
Performance can vary dramatically by:
province;
suburb;
neighbourhood;
property type;
development;
local demand;
crime levels;
infrastructure;
municipal services;
nearby development; and
the wider economy.
A house isn’t automatically a profitable investment merely because it’s a house.
3. Your Home Can Eventually Be Bond-Free
A major long-term benefit of ownership is the possibility of eventually having no home-loan repayment.
You will probably still face expenses such as:
municipal rates;
utilities;
insurance;
repairs;
security;
levies where applicable; and
general maintenance.
But eliminating a large monthly bond repayment can substantially change household finances later in life.
That can be particularly valuable when approaching retirement.
4. You Have More Control Over Your Home
Renters generally need to follow a lease and may require permission for significant changes.
Owners usually have much more control, subject to laws, municipal requirements and any applicable sectional-title or homeowners-association rules.
You may be able to:
renovate;
repaint;
change flooring;
improve the kitchen;
install certain fixtures;
improve security;
landscape the property; or
make other long-term improvements.
If creating a permanent home matters to you, this control has real value.
5. You Don’t Have a Landlord Deciding Whether to Renew Your Lease
Renting offers flexibility, but it also comes with uncertainty.
A landlord might eventually:
sell the property;
choose not to renew a lease;
change the rent subject to the agreement and applicable law; or
require you to move once the tenancy lawfully ends.
Ownership removes much of that particular uncertainty.
As long as you meet your financial and legal obligations, you have considerably more control over how long you remain in your home.
What Are the Disadvantages of Buying a House?
This is where the “buying is always better than renting” argument becomes too simplistic.
Owning a property can be expensive.
And the purchase price is not the full cost.
1. You Need More Money Than Just the Deposit
Suppose you want to buy a R1.5 million home.
Many first-time buyers focus almost entirely on:
“How much deposit do I need?”
But the transaction can involve other costs.
Depending on the transaction and financing, buyers can encounter costs connected to:
transfer;
conveyancing;
bond registration;
bank initiation or related fees;
property inspections;
moving;
insurance;
immediate repairs; and
transfer duty where applicable.
These costs can add up.
This is why using every rand you have for the deposit can leave you financially exposed immediately after becoming a homeowner.
How Does Transfer Duty Work When Buying a House?
Transfer duty is one of the most important property-purchase taxes to understand.
For acquisitions under the current rates effective from 1 April 2026, SARS says there was no change from the previous year’s transfer-duty schedule. Property values up to R1,210,000 fall within the 0% band, after which progressive rates apply. (South African Revenue Service)
The current SARS schedule is:
Property value
Transfer-duty rate
R1 – R1,210,000
0%
R1,210,001 – R1,663,800
3% above R1,210,000
R1,663,801 – R2,329,300
R13,614 + 6% above R1,663,800
R2,329,301 – R2,994,800
R53,544 + 8% above R2,329,300
R2,994,801 – R13,310,000
R106,784 + 11% above R2,994,800
Above R13,310,000
R1,241,456 + 13% above R13,310,000
These are progressive bands—not a single percentage charged against the entire property value once you cross a threshold. (South African Revenue Service)
Also, don’t assume that 0% transfer duty means zero transfer-related costs. Legal and registration costs can still exist.
When you’re renting and the geyser fails through ordinary circumstances, responsibility for dealing with the repair may fall to the landlord depending on the lease and cause.
When you own the house?
That problem is yours.
Homeowners can unexpectedly face expenses for:
leaking roofs;
burst pipes;
electrical faults;
plumbing;
geysers;
damp;
gates;
security systems;
appliances included in the property;
pools;
structural problems; and
general deterioration.
A R20,000 repair doesn’t care that you’ve already paid your bond this month.
This is one reason an emergency fund becomes even more important after buying.
3. You Pay Interest on the Home Loan
A bond allows you to buy a property without having the full purchase price in cash.
The trade-off is interest.
Over a long home-loan term, the total amount paid can be substantially higher than the original amount borrowed.
This is one reason you should never compare:
R10,000 rent
with
R10,000 bond repayment
and automatically conclude that buying costs the same.
The full comparison is much broader.
What Does a House Really Cost Each Month?
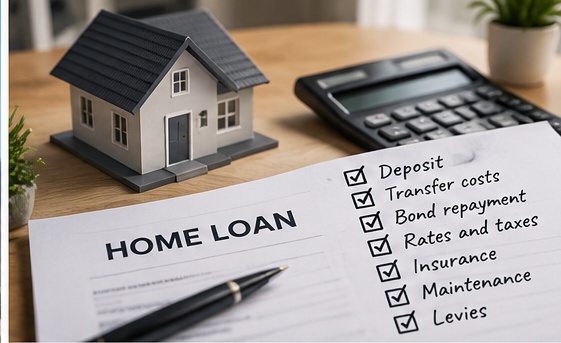
Home buyers should budget for more than the monthly bond repayment, including applicable transaction costs, rates, insurance, levies and maintenance.
A realistic homeowner budget might include:
Bond repayment
municipal rates and taxes
homeowners insurance
levies where applicable
maintenance provision
security
utilities
other property-specific expenses
Renters can face some of these expenses too, especially utilities.
But the point remains:
Bond repayment ≠ total cost of ownership.
This is one of the most important calculations to make before purchasing.
4. Interest Rates Can Change Your Bond Repayment
Many South African home loans have rates that move in relation to prevailing lending rates.
That means your monthly repayment may not remain unchanged for the entire bond term.
A household that can just afford its home at today’s repayment could come under pressure if its applicable interest rate increases.
This is why buyers should consider:
Could I still afford this property if my repayment increased?
rather than only:
Can I afford today’s repayment?
South Africa’s lending-rate framework is also evolving: the South African Reserve Bank has been consulting on transitioning away from the traditional prime lending-rate benchmark, so borrowers should check the actual pricing terms offered by their bank instead of relying on outdated assumptions about “prime.”
5. Buying Reduces Your Flexibility
Renting can make moving relatively straightforward once you’ve complied with your lease obligations.
Owning is different.
If you suddenly receive a job opportunity in another city, you may need to:
sell;
rent the property out;
leave it vacant; or
continue paying the bond while living elsewhere.
Selling takes time and involves costs.
This is why buying can make less sense for someone who expects significant life changes soon.
Examples include people who:
may move cities;
are considering emigrating;
expect their household size to change;
have unstable employment; or
aren’t sure where they want to settle.
Is Renting Really “Throwing Money Away”?
Comparing the total costs of buying and renting can help South Africans decide which option better suits their finances and lifestyle.
This is one of the most repeated statements in property discussions.
“Renting is throwing money away.”
It’s too simplistic.
Rent buys something valuable:
housing and flexibility.
Likewise, homeowners also spend money they don’t recover directly.
Examples include:
bond interest;
maintenance;
insurance;
rates;
certain levies;
transaction expenses; and
selling costs.
That doesn’t make buying bad.
It simply means both renting and owning contain expenses.
The correct comparison is not:
rent vs bond
It is closer to:
total cost of renting vs total cost of owning + opportunity cost + expected length of stay.
When Is Renting Better Than Buying?
Renting can be financially sensible when:
You expect to move soon
The transaction costs associated with buying and later selling can make short ownership periods unattractive.
Your income is unstable
A landlord still expects rent, but a long-term mortgage can create a much larger financial commitment.
You don’t have emergency savings
Buying a house while leaving yourself with R0 in savings is risky.
Comparable rent is substantially cheaper
Sometimes a property might be expensive to purchase but relatively affordable to rent.
You need flexibility
You may not want a 10-, 15- or 20-year property commitment.
You’re paying down expensive debt
Buying while carrying costly unsecured debt may place too much pressure on your cash flow.
When Does Buying Make More Sense?
Buying becomes more attractive when several conditions line up.
You have:
reasonably stable income;
manageable debt;
an emergency fund;
money for upfront costs;
a realistic deposit where needed;
room in your monthly budget;
a longer-term plan to remain in the property; and
a property you have researched properly.
Notice what isn’t on the list:
“The bank approved me.”
Approval is important.
But approval alone should not be your affordability test.
Should You Buy the Most Expensive House the Bank Approves?
In my view, usually not automatically.
If a lender says you qualify for R2 million, that doesn’t mean R2 million should become your shopping target.
Your bank’s affordability calculation cannot perfectly predict every future expense in your life.
You may later face:
children;
medical expenses;
job changes;
vehicle expenses;
family responsibilities;
higher rates;
repairs;
insurance increases; or
unexpected emergencies.
Buying below your absolute maximum can provide financial breathing room.
That breathing room has value.
Should You Have an Emergency Fund Before Buying?
Yes, preferably.
A home can generate expenses without warning.
If buying the property requires emptying your savings account completely, consider whether you’re financially ready.
An emergency fund can help cover situations such as:
temporary income loss;
urgent home repairs;
medical emergencies;
vehicle problems; or
unexpected bills.
Owning a R1.5 million asset while having R200 available in cash can still leave you financially vulnerable.
How Much Deposit Should You Put Down?
There isn’t one correct deposit percentage for everyone.
A larger deposit can potentially:
reduce the amount borrowed;
reduce monthly repayments;
reduce total interest;
strengthen your application; and
create immediate equity.
But putting all your savings into a deposit can also be risky.
You need to balance:
deposit size
against
cash reserves after purchase.
If the choice is between a slightly larger deposit and having absolutely no emergency savings, retaining some liquidity may be important.
The exact decision depends on your finances and the home-loan offer.
Should First-Time Buyers Purchase a House or Apartment?
potentially easier entry into the property market.
But they can also involve:
levies;
special levies;
body-corporate rules;
shared decision-making;
limited space; and
restrictions on certain alterations.
Freestanding homes can offer:
more space;
privacy;
greater control;
gardens;
expansion possibilities; and
fewer shared-building issues.
But maintenance and security costs can be higher.
Don’t buy an apartment purely because the monthly bond looks affordable.
Check the levy, financial health of the body corporate, rules and any potential special levies.
What Should You Check Before Buying a Property?
Don’t fall in love with the kitchen and forget the building.
Investigate the property carefully.
Pay attention to:
roof condition;
damp;
cracks;
plumbing;
electrical systems;
water pressure;
geyser;
drainage;
security;
boundaries;
neighbourhood;
municipal services;
rates;
levies;
body-corporate finances;
planned developments nearby; and
obvious structural concerns.
Where appropriate, paying for a professional property inspection can be worth considering.
A beautiful coat of paint can hide expensive problems.
Is Property Always a Good Investment?
No.
This deserves a direct answer.
A property can:
increase in value;
stagnate;
underperform inflation;
become difficult to sell; or
lose value.
Even when the selling price rises, you should consider what you spent on:
interest;
improvements;
maintenance;
insurance;
transaction costs; and
selling expenses.
A property bought for R1 million and sold for R1.3 million did not necessarily produce a clean R300,000 profit.
The real calculation is more complicated.
What About Capital Gains Tax When You Sell?
Tax can also matter when disposing of property.
For individuals, SARS currently provides a R3 million exclusion on a capital gain or loss from the disposal of a qualifying primary residence, alongside the broader capital-gains-tax rules. From the 2027 tax year, the annual capital-gain/loss exclusion for individuals and special trusts is R50,000. (South African Revenue Service)
That does not mean every home sale below a certain selling price is automatically tax-free. The tax treatment depends on the gain, whether the property qualifies as a primary residence, how it was used and other circumstances.
For complex cases—especially where part of a property was rented out or used for business—professional tax advice can be worthwhile.
This is why generic claims like “buying always wins” or “renting always wins” aren’t useful.
What If the Renter Invests the Difference?
This changes the argument substantially.
Suppose the renter consistently invests the R4,800 monthly difference instead of spending it.
Over many years, that investment could become a meaningful asset.
The comparison is then no longer:
Homeowner with asset vs renter with nothing.
It becomes:
Homeowner’s property equity vs renter’s investment portfolio.
Of course, many renters don’t invest the difference.
But many homeowners also don’t achieve the property returns they imagined.
The outcome depends heavily on behaviour and actual numbers.
Is Buying a House Worth It for a Young South African?
It can be.
Age alone shouldn’t decide.
A 25-year-old with:
stable employment;
savings;
manageable debt;
a long-term location;
an emergency fund; and
an affordable property
could be better prepared than a 40-year-old with heavy debt and unstable income.
Likewise, being young may make renting attractive because career and lifestyle changes are more likely.
Don’t buy because social media says:
“You should own property by 30.”
Your financial position matters more than somebody else’s timeline.
Should You Buy a House If You Have Debt?
It depends on the debt.
Having some debt doesn’t automatically prevent responsible homeownership.
But expensive unsecured debt deserves attention.
Examples might include:
credit-card balances;
personal loans;
retail accounts; and
other high-cost borrowing.
Adding a large home loan on top of an already strained monthly budget can create serious pressure.
Before buying, calculate your entire debt burden, not merely whether the bank will approve another loan.
Should You Buy a House If Your Job Isn’t Secure?
This requires extra caution.
A home loan is a long-term obligation.
If your income disappears, the bond doesn’t disappear with it.
Consider:
emergency savings;
alternative income;
income protection where appropriate;
whether another household member earns income;
your industry’s stability; and
how easily you could reduce expenses.
If one missed salary would immediately make your bond impossible to pay, the property may be too expensive for your current financial position.
Is Buying Property Better Than Investing in Shares?
They solve different problems.
A primary residence provides:
somewhere to live + potential wealth accumulation.
An investment portfolio primarily aims to:
grow capital/income.
Property can offer:
tangible ownership;
leverage through a home loan;
housing security; and
potential appreciation.
Investments such as diversified funds can offer:
easier diversification;
greater liquidity;
lower maintenance responsibilities; and
easier partial selling.
You don’t necessarily need to choose only one forever.
Many financially secure households eventually own a home and invest in financial assets.
How Long Should You Stay in a House for Buying to Make Sense?
There isn’t a universal number.
But generally, the shorter your expected stay, the more carefully you should scrutinise buying.
Why?
Because buying and selling involve transaction costs.
If you buy today and need to sell shortly afterwards, property appreciation may not have had enough time to offset those expenses.
Someone expecting to relocate within one or two years has a very different decision from someone expecting to remain for 10 or 20 years.
What Happens If You Can’t Pay Your Bond?
This is one of the biggest risks of homeownership.
If you’re experiencing financial difficulty, don’t simply ignore missed payments and hope the problem disappears.
Contact the lender as early as possible.
A mortgage is secured against the property, and prolonged default can ultimately put the home at risk through legal enforcement processes.
This is another reason why buying below your maximum affordability and maintaining emergency savings can be valuable.
Is Buying a House Worth It If You Plan to Rent It Out Later?
Potentially, but then you should analyse the property partly as an investment.
Consider:
achievable rental income;
vacancies;
maintenance;
rates;
levies;
insurance;
agent fees;
taxes;
tenant risk; and
bond costs.
Don’t simply assume:
“My tenant will pay my bond.”
The rent you collect and the total cost of owning the property are two different numbers.
A rental property can still require money from you every month.
Should You Buy in a New Development?
New developments can be attractive because they may offer:
modern finishes;
lower immediate maintenance;
security;
amenities; and
developer incentives.
But buyers should still investigate:
developer reputation;
body-corporate projections;
levies;
future construction;
unit density;
parking;
resale competition;
defects;
location; and
expected supply.
A brand-new kitchen doesn’t automatically make a property a good investment.
Should You Buy a Fixer-Upper?
A cheaper property needing renovation can create an opportunity.
But only if you understand the costs.
A house that appears R200,000 cheaper might require:
R100,000 roof repairs;
R80,000 electrical work;
R50,000 plumbing;
R100,000 kitchen work; and
additional unforeseen expenses.
Get realistic estimates.
DIY optimism isn’t a budget.
What Are the Biggest Mistakes First-Time Home Buyers Make?
Common mistakes include:
Buying at the maximum approved amount.
Forgetting transfer and bond-related costs.
Having no emergency fund after purchase.
Ignoring levies.
Underestimating maintenance.
Failing to inspect the property.
Buying emotionally.
Assuming prices can only rise.
Ignoring the neighbourhood.
Focusing only on today’s interest rate.
Not comparing home-loan offers.
Buying because of pressure from family or social media.
Assuming rent is always wasted money.
Failing to plan for income loss.
Forgetting that selling also costs money.
Avoiding these mistakes may matter more than finding the “perfect” property.
Questions to Ask Yourself Before Buying
Before signing an offer to purchase, answer these honestly:
Question
Why it matters
Is my income stable?
The bond is long term
Do I have emergency savings?
Repairs and income shocks happen
Can I afford the full ownership cost?
Bond isn’t the only expense
What if rates rise?
Repayments may change
Will I stay here long term?
Short ownership can be costly
Do I have expensive debt?
Cash flow may already be strained
Have I researched the area?
Location affects lifestyle and value
Have I inspected the property?
Hidden defects can be expensive
Do I understand rates and levies?
They affect monthly affordability
Am I buying because I want to—or because I feel pressured?
Emotional purchases can be costly
If several answers concern you, waiting may be the smarter decision.
Is It Better to Buy a Cheap House First?
For many first-time buyers, starting below their maximum budget can be sensible.
Your first home does not have to be:
your dream home;
your forever home;
the biggest house you can qualify for; or
a property designed to impress other people.
A smaller affordable property can allow you to experience ownership while maintaining financial flexibility.
The goal shouldn’t be:
“What’s the most expensive house I can buy?”
A better question is:
“What house can I comfortably afford while still building the rest of my financial life?”
Our Opinion: Is Buying a House Worth It in South Africa?
Yes, buying a house can absolutely be worth it in South Africa—but ownership should be treated as a long-term financial commitment, not an automatic milestone.
News Domain’s view is that buying becomes particularly attractive when you:
have stable income;
have emergency savings;
can afford upfront costs;
aren’t overloaded with expensive debt;
can comfortably afford the total monthly ownership cost;
plan to remain in the property for years; and
have researched the property carefully.
Renting can be the better decision when:
you need flexibility;
your career or location may change;
your income is uncertain;
you have little savings;
buying would consume nearly all your monthly income; or
renting an equivalent property costs substantially less.
The worst reason to buy is:
“Everyone says renting is a waste of money.”
The best reason is:
“I’ve done the numbers, I understand the risks, I can comfortably afford it, and ownership fits my long-term plans.”
Frequently Asked Questions
Is buying a house worth it in South Africa?
It can be worth it if you can comfortably afford the full cost of ownership, have emergency savings and expect to keep the property for several years. Renting may be better when flexibility and lower short-term costs are more important.
Is renting cheaper than buying in South Africa?
Sometimes. It depends on the property, location, bond terms, rent, levies, rates, insurance and maintenance. Compare the total cost, not rent against bond repayment alone.
Is renting throwing money away?
No. Rent pays for accommodation and flexibility. Homeowners also pay costs that don’t directly create equity, including interest, maintenance, insurance and rates.
Do you pay transfer duty on every house?
No. Under the SARS rates effective from 1 April 2026, the first R1.21 million of property value falls in the 0% transfer-duty band. Progressive rates apply above that level. Other transaction costs can still apply. (South African Revenue Service)
Is transfer duty the same as transfer costs?
No. Transfer duty is a tax. Legal, conveyancing, registration and other transaction expenses are separate considerations.
Should I buy a house with no savings?
Generally, that creates additional risk. Homeowners can face unexpected repairs and income shocks, making emergency savings valuable.
Should I use all my savings as a deposit?
Not automatically. A larger deposit can reduce borrowing, but leaving yourself without emergency funds can create financial vulnerability.
Is property guaranteed to increase in value?
No. Property performance varies by area, market conditions and the individual property.
Should I buy the maximum amount the bank approves?
Not necessarily. Approval tells you what the lender is willing to finance under its assessment. Your own budget should determine what you can comfortably afford.
Is buying better if I plan to stay for 10 years?
A longer holding period can make ownership more attractive because there is more time to build equity and potentially absorb transaction costs, although returns are never guaranteed.
What happens if interest rates increase?
If your home-loan rate is variable, your repayment can increase. Check your specific loan agreement and stress-test your budget before buying.
Should I buy an apartment as my first property?
It can be a good option, but check levies, body-corporate finances, rules, special-levy risk, maintenance and resale conditions before buying.
Can I make money renting out my house?
Potentially, but rental income must be compared against vacancies, maintenance, rates, levies, insurance, taxes, agent costs and financing expenses.
Final Verdict
If you came here asking is buying a house worth it in South Africa, the answer is:
Yes—for the right person, at the right price, at the right stage of their financial life.
Homeownership can provide security, equity and a valuable long-term asset.
But a house is not automatically a good financial decision simply because you qualify for a bond.